The chip technology company reports $1.44 billion in quarterly revenue, driven by licensing and AI demand, but slower royalty growth and smartphone market concerns overshadow its strong results.
Arm Holdings reported record second-quarter revenue of $1.44 billion on November 4, 2026, but its shares fell as investors focused on weaker-than-expected royalty income. The British semiconductor technology company benefited from growing demand for artificial intelligence infrastructure, although its smartphone-related business continued to face challenges.
Revenue increased 27% from the same period last year, marking Arm’s fifth consecutive quarter of annual growth exceeding 20%. However, royalty revenue rose just 8% to $670 million, substantially below Wall Street expectations.
The results highlighted a growing divide between Arm’s expanding opportunities in AI computing and its dependence on established smartphone markets. Shares declined in after-hours trading Wednesday, with selling accelerating during Thursday’s broader technology stock downturn.
Record Revenue Fails to Satisfy Investors
Arm’s fiscal second quarter ended September 30, 2026. The company reported total revenue of approximately $1.44 billion, its highest second-quarter figure on record.
The results exceeded analysts’ average revenue estimate of $1.38 billion, according to Reuters. Adjusted earnings reached 52 cents per share, also above the expected 47 cents.
Despite those stronger headline numbers, investors were disappointed by the performance of Arm’s royalty business. The company collected $670 million in royalty revenue, compared with the approximately $721 million analysts had anticipated.
Royalty income is particularly important because Arm receives payments when customers ship semiconductor chips incorporating its technology. These payments provide insight into the commercial use of Arm’s designs across smartphones, servers, automobiles and other electronic devices.
Licensing and other revenue increased 50% to $773 million, exceeding analyst expectations of approximately $625 million. The substantial increase helped compensate for the slower growth in royalties.
However, licensing revenue can fluctuate depending on the timing and size of customer agreements. A strong quarter of licensing activity does not guarantee that chip shipments and corresponding royalty payments will increase at the same pace.
That distinction contributed to the market’s negative reaction. Investors wanted stronger evidence that demand for Arm’s technology was translating into sustained growth in chips being shipped by its customers.
Arm’s shares fell following the earnings release and continued declining Thursday. The stock had already experienced considerable gains earlier in 2026, leaving investors sensitive to any signs that growth might fall short of expectations.
Smartphone Market Weakness Affects Royalties
Arm’s technology remains a central component of the global smartphone industry. Its processor architecture is used in virtually all modern smartphones, making mobile devices an important source of recurring royalties.
The company attributed part of the slowdown in royalty growth to rising memory prices and their effects on smartphone demand. Higher memory costs can increase the expense of manufacturing phones, potentially affecting production volumes and consumer purchasing decisions.
Arm also benefited from higher royalty rates associated with newer processor designs. However, those improvements were not enough to overcome weaker conditions in parts of the smartphone market.
The company continues encouraging customers to adopt Armv9 technology and more advanced computing subsystems. These newer designs can generate higher royalty payments than older products, providing opportunities for revenue growth even when overall chip shipments increase more slowly.
Yet the smartphone market remains sensitive to consumer spending, replacement cycles and manufacturing costs. A slowdown in handset sales can affect the volume of chips using Arm technology.
The challenge for Arm is balancing its established mobile business with faster-growing opportunities in cloud computing and artificial intelligence. Investors are watching whether those newer markets can become large enough to offset fluctuations in smartphone demand.
AI Data-Center Royalties Double
Artificial intelligence infrastructure was one of the strongest areas of Arm’s quarterly performance. The company reported that data-center royalty revenue doubled compared with the same period last year.
Large cloud computing companies are increasingly deploying processors based on Arm architecture. These chips can provide advantages in energy efficiency, an important consideration as data centers consume growing amounts of electricity.
Arm’s technology is used in server processors developed by major cloud providers, including Amazon Web Services, Google and Microsoft. The company also benefits from partnerships involving Nvidia and other businesses supplying AI computing infrastructure.
According to Arm’s shareholder letter, its server technology accounted for more than 50% of deployments among leading hyperscale cloud providers in calendar 2025. Management expects that share to exceed 60% by the end of 2026.
Those figures reflect Arm’s expanding presence in a market historically dominated by processors using competing architectures. Increasing adoption could create additional royalty opportunities as cloud providers purchase and deploy more servers.
Arm also reported that royalty revenue from what it calls physical AI increased 50% year over year. That category includes applications involving automotive technology and robotics.
Although the data-center results were strong, Arm did not identify a total dollar amount for that segment in its earnings announcement. Consequently, the reported doubling cannot be directly compared with the company’s overall royalty revenue without additional information.
New Arm AGI CPU Expands Business Strategy
Arm is also developing a new business around selling its own processor products rather than relying exclusively on licensing technology to other chip designers.
The company’s Arm AGI CPU is intended to serve demanding AI and cloud computing workloads. Management said customer interest has strengthened and that it has secured purchase orders extending through calendar 2027.
Arm expects its first commercial AGI CPU deliveries during the fourth quarter of fiscal 2027. The company also said it has become more confident in its ability to generate up to $2 billion in revenue from the product across fiscal 2027 and fiscal 2028.
That amount is a projection rather than guaranteed sales. Actual revenue will depend on customer demand, manufacturing availability and the successful delivery of the processors.
Oracle Cloud Infrastructure has announced plans to offer computing instances based on the Arm AGI CPU in 2027. The relationship provides another potential outlet for the company’s expanding server technology.
Chief Executive Officer Rene Haas has emphasized that demand for AI computing is creating opportunities across cloud services, personal devices and autonomous systems. Arm increasingly views its technology as a foundation for several computing markets rather than primarily a smartphone processor architecture.
Moving into direct processor sales also introduces new considerations. The company must manage manufacturing arrangements, supply commitments and customer deliveries alongside its traditional intellectual-property licensing business.
Chip Shipments Reach New Quarterly Record
Arm reported that its partners shipped more than 10 billion Arm-based chips during the quarter. That represented an increase of approximately 1.5 billion chips from a year earlier.
The shipments covered a broad range of electronic products, including smartphones, computers, industrial systems and connected devices. They were not limited to AI processors or data-center equipment.
The figure illustrates the scale of Arm’s technology ecosystem. Its designs are used across products manufactured by numerous semiconductor companies, creating opportunities for royalty income from many different markets.
Arm also signed three new Total Access agreements during the quarter, bringing its active subscriptions under that program to more than 60. These agreements allow customers to access a broader selection of Arm technologies as they develop future products.
Four additional compute subsystem licenses were signed, including two related to data-center chips and two for smartphones. The agreements could support future business, although revenue from resulting chip shipments will depend on customer development and production schedules.
The company reported that annualized contract value increased 12% to $1.79 billion. Management uses this measure to help assess underlying licensing activity when individual quarterly agreements cause revenue fluctuations.
Profit Declines Despite Higher Revenue
Arm’s strong sales growth did not produce a corresponding improvement in reported net income. Profit calculated under generally accepted accounting principles fell to $130 million from $238 million a year earlier.
That represented a decline of approximately 45%. GAAP earnings per share dropped from 22 cents to 12 cents.
The company continued increasing investment in research and development as it expanded its technology offerings. Its newer processor business and ongoing product development are creating additional expenses.
On an adjusted basis, however, Arm reported net income of $566 million, up from $417 million a year earlier. Adjusted earnings per share increased 33% to 52 cents.
The difference between GAAP and adjusted earnings reflects exclusions for certain expenses and other accounting adjustments. Investors examine both measures to assess operating performance, expenses and profitability.
Arm also reported non-GAAP free cash flow of $110 million, down from $411 million a year earlier. The decline provides another financial measure for investors to monitor as the company increases spending on development.
Third-Quarter Forecast Offers Limited Reassurance
For its fiscal third quarter, Arm expects revenue of approximately $1.54 billion, with a possible variation of $50 million in either direction. The midpoint was slightly above analysts’ average forecast of $1.53 billion.
The company projected adjusted earnings per share of approximately 56 cents, plus or minus four cents. Adjusted operating expenses are expected to reach about $825 million as Arm continues investing in technology development.
Although the forecast indicates further revenue growth, it did not significantly exceed market expectations. That limited upside contributed to concerns about whether the company’s valuation already reflected much of its anticipated AI expansion.
JPMorgan analyst Harlan Sur maintained an Overweight rating on Arm but reduced his price target from $255 to $245. The adjustment reflected a more cautious assessment of the company’s near-term prospects despite confidence in its longer-term business opportunities.
Arm’s next earnings report will provide another measure of whether data-center adoption and new licensing agreements are generating faster royalty growth. Investors will also be watching smartphone demand, memory prices and progress toward the first commercial Arm AGI CPU deliveries.
For now, the company faces a clear financial test: translating strong demand for its technology into sustained royalty growth and improved profitability. Its record second-quarter revenue demonstrates expanding customer interest, but Thursday’s stock decline showed that investors are looking for stronger results across the entire business.
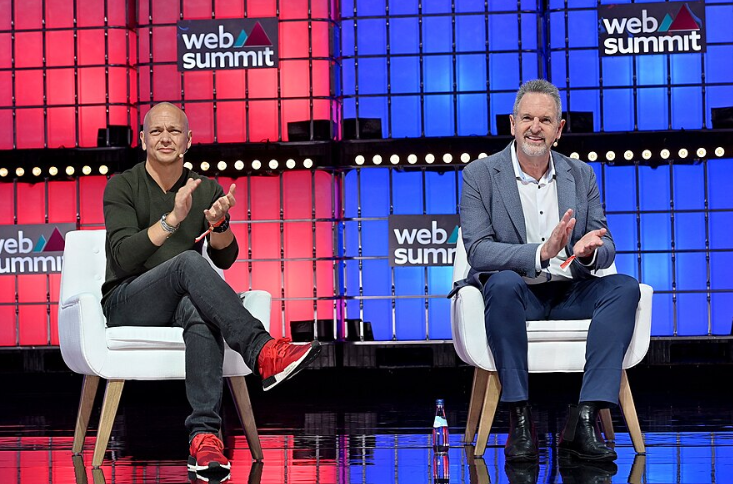
IMAGE: Tony Fadell and Rene Haas Source RC1_6215 Author Web Summit CC2