Mark Zuckerberg is placing the Muse AI assistant at the center of Meta’s future, but rising infrastructure costs, legal expenses and questions about profitability present major challenges.
Meta Platforms is making its Muse artificial intelligence assistant a centerpiece of its business strategy after attracting more than 10 million users in the United States and Canada. CEO Mark Zuckerberg highlighted the product’s early growth during the company’s third-quarter earnings call on October 21, 2026, while outlining plans to expand AI services, commerce and wearable technology.
The announcement came alongside quarterly revenue of $64.6 billion, a 26% increase from the previous year. However, substantial legal expenses and investment in artificial intelligence infrastructure weighed heavily on operating profits.
Zuckerberg described Muse as an important step toward his goal of making personal AI assistants available to billions of people. The product allows users to delegate tasks, research information and make purchases through a conversational interface.
Approximately 25% of people who have set up Muse use it daily, according to Zuckerberg. That early engagement rate is more than twice what Meta recorded when Threads launched, although the services serve different purposes.
The results suggest that Meta is beginning to attract consumers to an AI product that operates separately from its established social media platforms. Turning that early interest into a sustainable business remains a more difficult challenge.
Muse Finds an Early Audience
Meta introduced Muse in September as a personal AI agent designed to complete tasks rather than simply answer questions. Users can interact with the assistant through its dedicated application or supported messaging services.
Unlike conventional chatbots, Muse is designed to carry out activities involving multiple steps. Its capabilities include researching products, comparing options and assisting with online transactions.
Digital market research firm Sensor Tower reported that Muse surpassed 10 million downloads in North America during its first 35 days. PYMNTS reported the figures on October 20, noting that the application reached that milestone faster than several competing AI assistants.
Those downloads demonstrate considerable early interest, but they do not necessarily represent 10 million customers making regular use of the service. Continued engagement will provide a more meaningful measure of its appeal.
Meta is also investing in increasingly capable models to support the assistant. Earlier in October, the company announced Muse Wonder and Muse Wonder Full, describing them as its most advanced AI models for completing complex personal and professional tasks.
The systems are designed to help users manage activities such as understanding documents, handling administrative processes and developing software. Meta has also introduced memory and task-management features intended to support more complicated work.
Muse Wonder is initially available through developer services and Muse Code. Meta plans to incorporate the technology into the consumer assistant, beginning with subscribers.
Shopping Becomes a Major Opportunity
One of Muse’s most important early uses involves online shopping. Zuckerberg said more than one-quarter of its users have engaged with shopping features, with average purchases exceeding $200.
The activity provides Meta with a possible revenue source beyond advertising. Instead of earning money primarily by displaying advertisements, the company could collect fees when its assistant helps customers complete purchases.
Meta is exploring several approaches to monetization, including transaction fees, paid subscriptions and AI services for businesses. These plans could allow the company to earn revenue directly from the work its AI systems perform.
The potential market has attracted attention from financial analysts. In an October assessment reported by Reuters, Citigroup estimated that Muse could eventually generate more than $27 billion in annual revenue by 2030.
That figure is a forecast rather than a company commitment. It depends on substantial growth in users, shopping activity and successful monetization.
There are also practical obstacles. AI assistants must be able to interact with merchant websites, payment systems and other commercial services while respecting security and privacy requirements.
Access restrictions imposed by retailers and online platforms could limit the number of transactions Muse can complete. The company must also ensure that operating the assistant does not cost more than the revenue it generates.
AI Costs Remain a Major Obstacle
Zuckerberg acknowledged that Muse is not yet profitable because of the computing resources required to operate it. The company needs major efficiency improvements before it can economically deliver the service to a much larger audience.
During the earnings discussion, Meta outlined a goal of improving Muse’s computing efficiency by more than tenfold over the coming year. Achieving that target would help reduce the cost of handling individual requests.
The company is already applying its own AI technology to internal operations. Zuckerberg described tests involving content-understanding systems that reduced processing costs by more than 80%.
Those results suggest that more efficient models could produce meaningful savings. However, improvements achieved during testing do not guarantee equivalent savings across every commercial application.
Meta has also limited Muse’s initial consumer rollout to the United States and Canada. The company expects to expand internationally, but the timing will depend partly on its ability to support additional demand.
Infrastructure spending remains central to the strategy. Meta continues to invest heavily in data centers, servers and specialized computing equipment needed to train and operate advanced AI systems.
Its latest outlook calls for capital expenditures of approximately $135 billion to $145 billion during 2026. Such spending reflects the enormous scale of Meta’s ambitions and the financial risks involved.
Advertising Business Continues to Grow
Although Muse represents a new direction, advertising remains Meta’s primary source of revenue. The company’s third-quarter advertising revenue reached approximately $63.1 billion, increasing 26% from the previous year.
Meta reported higher advertising demand alongside improvements in the technology used to recommend content and deliver advertisements. Ad impressions increased 10%, while the average price per advertisement rose 14%.
Zuckerberg said Facebook and Instagram reached new engagement highs, supported by video viewing and improved content recommendations. He also said Threads had surpassed X in monthly active users.
WhatsApp continued experiencing strong messaging activity, giving Meta another large platform through which it can introduce AI-powered services.
The company’s advertising operations increasingly rely on machine learning to identify relevant content and match advertisements with potential customers. Improvements to those systems can increase revenue without requiring equivalent growth in user numbers.
Meta also reported progress with its AI Business Assistant, which helps advertisers plan campaigns, evaluate performance and create marketing materials.
According to company estimates, advertisers adopting the assistant’s recommendations generated nearly 5% more conversions at the same cost per conversion. They also increased their advertising spending by approximately 9% compared with similar advertisers who did not adopt the recommendations.
These results are company estimates and do not establish that every advertiser will receive comparable benefits. Nevertheless, they demonstrate how Meta hopes to use AI to strengthen its established advertising business while developing new products.
Another growing area is creator advertising. Meta said partnership advertising revenue increased more than 97% from the previous year, reaching an annualized revenue rate above $15 billion.
The company has also expanded its Creator Marketing Hub, making more than 10 million creators discoverable to advertisers. Its AI tools are intended to simplify finding suitable creators and organizing advertising partnerships.
Legal Expenses Reduce Quarterly Profit
Meta’s strong revenue growth did not translate into comparable operating profit growth. Operating income fell approximately 37% from the previous year to $13 billion, producing an operating margin of about 20%.
A major reason was a legal charge of approximately $9.9 billion associated with a settlement involving state attorneys general and concerns about the effects of social media on young people.
The expense significantly increased Meta’s reported quarterly costs. Without that charge, management said operating income would have increased approximately 11% from the previous year.
The company reported net income of approximately $9.86 billion, equivalent to diluted earnings of $3.83 per share. Its overall expenses reached approximately $51.6 billion.
Meta also reported a substantially smaller workforce following restructuring earlier in the year. Its employee count stood at approximately 66,800, down sharply from the previous quarter.
For the fourth quarter, Meta forecast revenue between $73 billion and $76 billion. The outlook reflects expectations that advertising will remain strong even as spending on new technologies continues.
Stock Changes and Smart Glasses Support the Strategy
Meta also announced plans to issue a new class of nonvoting shares through a transaction expected in January 2027. The change would effectively create a two-for-one stock split while allowing the company greater flexibility in funding investments and acquisitions.
The proposed structure would also preserve Zuckerberg’s control over major corporate decisions. Investors will be watching how Meta balances shareholder interests with its plans for continued AI expansion.
Another important part of the strategy involves smart glasses. Meta sees wearable devices as a way for people to use personal AI assistants throughout the day without constantly relying on smartphones.
Muse could eventually help users understand their surroundings, retrieve information and complete tasks through voice-based interactions. Such features would connect the company’s AI investment with its existing work on wearable technology.
Reality Labs, the division responsible for several of Meta’s hardware initiatives, continues to generate substantial losses. Management expects those losses to remain significant as development continues.
For now, Muse’s early adoption offers evidence of consumer interest, while Meta’s advertising business provides the revenue needed to support further development.
The next challenge will be turning millions of downloads into regular paying customers without allowing computing costs to overwhelm potential revenue. Meta’s planned expansion of Muse, improvements in model efficiency and introduction of new subscription services will provide important tests of Zuckerberg’s strategy during 2027.
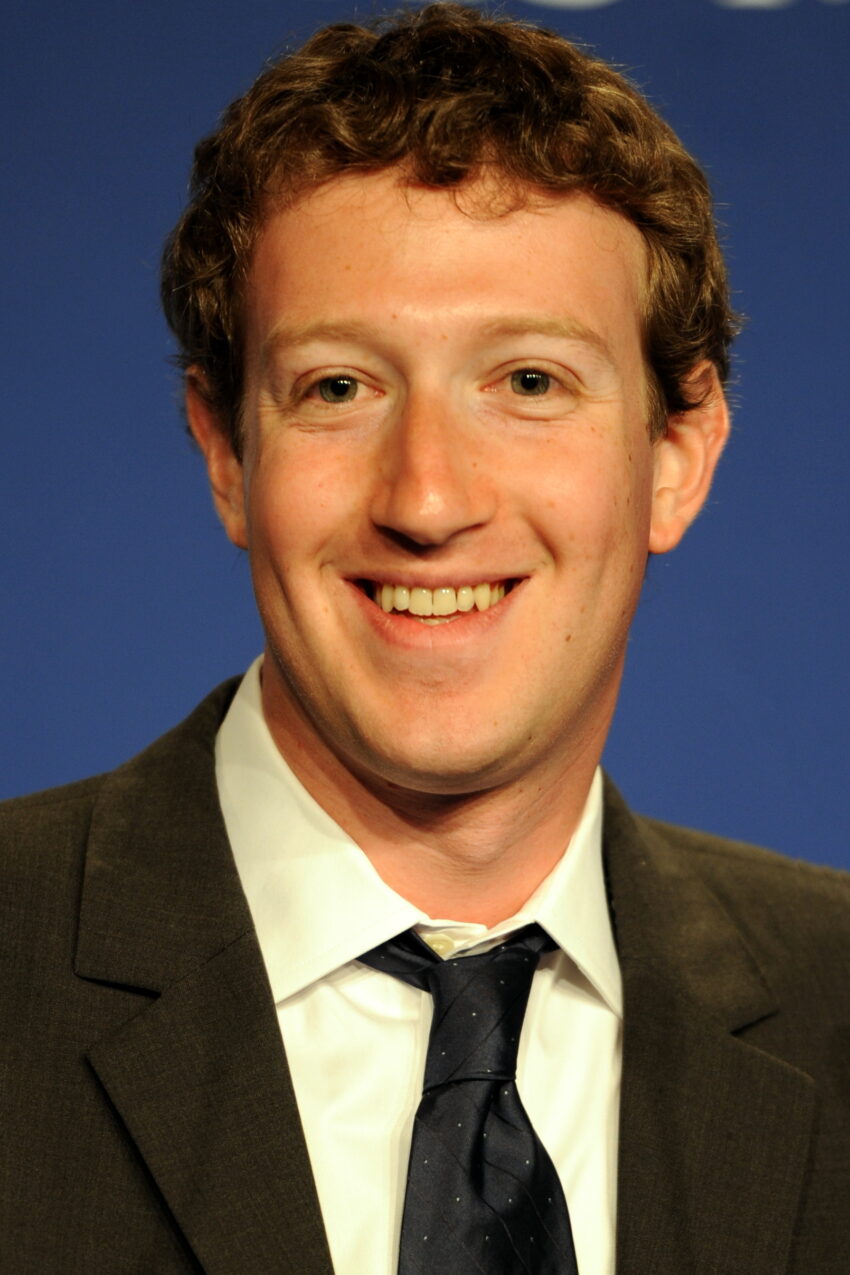
IMAGE: Mark Zuckerberg, Founder & CEO of Facebook, at the press conference about the e-G8 forum during the 37th G8 summit in Deauville, France.. Photo: Guillaume Paumier / Wikimedia, taken 2011-05-26, CC BY 3.0