The 10-year Treasury yield rose above 5% and reached 5.041% on Tuesday, its highest level since 2007. This increase follows a temporary spike above the same level in 2023 and reflects broader macroeconomic concerns. The rise in long-term yields has shifted how investors price assets across global markets, affecting both equities and fixed income securities. Reuters reported that the average 10-year government bond yield across the Group of Seven economies reached its highest level since 2008.
Market participants are now adjusting their portfolios as the Federal Reserve’s preferred PCE inflation measure remains above its 2% target. The PCE price index was up 3.7% from a year earlier in July. Investors expect that interest rates will stay elevated longer than previously anticipated to manage persistent inflationary pressures. Escalating conflicts in the Middle East have contributed to higher crude oil prices, adding to imported inflation and reinforcing the case for continued tight monetary policy. Fed Chair Kevin Warsh said in August that inflation remained too high and that the Federal Reserve’s main focus should be on prices.
The growing federal debt burden also plays a role in pushing up Treasury yields. The federal budget deficit totaled about $955 billion in the first seven months of the 2026 fiscal year. Total U.S. public debt reached a record $40 trillion in August. The Congressional Budget Office projects net interest costs of about $1 trillion in fiscal 2026, equal to roughly 14% of projected federal outlays. Concerns about large deficits, heavy government borrowing and higher term premiums have also helped push long-term yields higher.
Rising Treasury yields are forcing investors to reevaluate their holdings in both stocks and bonds. Sector divergence has become more pronounced, especially between dividend stocks and growth equities. Dividend-focused stocks now face competitive pressure from high-yield Treasury bonds, which offer more predictable returns. Higher Treasury yields can make government bonds more attractive compared with dividend-paying stocks, putting pressure on some equity valuations.
Growth stocks have also seen their valuations decline due to rising discount rates in the discounted cash flow model. Higher discount rates reduce the present value of earnings expected farther into the future. Technology firms with strong forward-looking growth profiles have experienced valuation drops.
Small-cap stocks are particularly vulnerable in this environment, as higher interest rates raise financing costs for firms with weaker balance sheets. These companies often have less stable cash flows and limited capacity to handle increased interest expenses.
The impact of rising yields extends beyond equities into the housing market, where mortgage rates are increasing. Higher credit costs have contributed to rising mortgage rates, affecting homebuyers and the broader real estate industry. The housing market’s recovery from the pandemic has been slowed by these higher rates, reducing demand and earnings for real estate stocks. A Reuters poll found the average 30-year mortgage rate had risen to about 6.85% since the Iran conflict began in late February.
Despite the challenges, some sectors continue to show resilience, particularly in AI. The artificial intelligence industry has remained an important source of earnings and investment growth, though AI-related stocks have also been volatile. Large technology companies with strong cash positions may be better able to absorb higher financing costs than smaller firms. Reuters reported that AI-related investment and earnings growth have helped support the broader stock market this year.
Analysts said investors are watching whether the move above 5% becomes sustained rather than treating a single move as a lasting trend. The overall stock market rally has been supported by AI-driven companies, despite broader headwinds in other areas. Reuters reported Tuesday that the S&P 500 remained close to its August record despite the rise in bond yields.
On Tuesday, U.S. stocks fell as the 10-year Treasury yield climbed above 5%, with investors reacting to rising oil prices and an upcoming Federal Reserve decision. The move pushed the yield to 5.041%, its highest point since 2007. Bond prices fell in response to the rising yields, which is a standard market reaction. Oil prices rose after Saudi Arabia shut down a key pipeline, raising concerns about tighter supplies and inflation. The S&P 500 closed down 0.4%, the Dow fell 0.6% and the Nasdaq dropped 0.8%.
Markets were pricing in about a 93% chance of a quarter-point Fed rate increase on Wednesday, according to The Wall Street Journal. Warsh is expected to speak after the Federal Reserve announces its rate decision Wednesday. His most recent major policy remarks stressed that inflation remained above target while avoiding firm forward guidance on future rate moves. Warsh took office as Fed chair on May 22.
On Monday, AI-related stocks were among the biggest losers after industry leaders called for a slowdown in advanced AI development and OpenAI said it would not go public this year. Nvidia fell 3.4%, Corning dropped about 14% and the Philadelphia Semiconductor Index fell 5.9% on Monday. Nvidia recovered 0.6% on Tuesday.
The 5% Treasury yield level is widely watched because higher risk-free returns can put pressure on stock valuations. Asian markets were mixed Tuesday as investors reacted to higher bond yields, oil prices and upcoming central bank decisions. Japan’s Nikkei 225 rose 0.19%, while MSCI’s broad index of Asia-Pacific shares outside Japan slipped 0.12%.
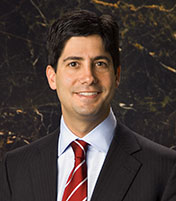
IMAGE: Kevin Warsh, then a member of the Board of Governors of the Federal Reserve System. Photo: Federal Reserve / Wikimedia Commons, circa 2006, public domain. Wikimedia lists the date only as approximately 2006, so I would not use “2006-00-00” in the published caption.
IMAGE: Kevin Warsh, member of the Board of Governors of the Federal Reserve.. Photo: Federal Reserve / Wikimedia, taken 2006-00-00, Public domain