Treasury Secretary Scott Bessent is facing criticism for expanding the government’s bond-buyback program, with former mentor Stanley Druckenmiller warning that such actions could harm the nation’s fiscal credibility. The Treasury announced on Wednesday that it would double its long-dated Treasury buybacks from $2 billion to at least $4 billion per operation, focusing on bonds with maturities between ten and thirty years. This move followed a rise in the 30-year Treasury yield to its highest level in 19 years, as investors demanded higher returns due to concerns over Washington’s fiscal outlook.
Druckenmiller argued that the Treasury’s actions were not about managing liquidity but instead aimed at manipulating bond prices, a move he said could have consequences far beyond the $4 billion in spending, according to bizpacreview.com. He pointed out that there was no sign of a broken Treasury market, noting orderly trading and low volatility, suggesting that the yield increase reflected broader economic concerns rather than dysfunction. The bond market was responding to a worsening fiscal picture, including inflation above the Federal Reserve’s target, a federal deficit approaching 6% of GDP, and national debt surpassing $40 trillion.
Druckenmiller emphasized that the bond market was not acting like a vigilante but instead reflecting the real challenges facing the country’s finances. His criticism is especially striking given his long-standing relationship with Bessent, who worked under him at George Soros’ hedge fund before becoming chief investment officer. Druckenmiller warned that suppressing long-term yields could remove one of the few mechanisms forcing Washington to deal with its fiscal issues.
He said every basis point of artificial yield suppression acted as a subsidy for delay in addressing these problems. Additionally, he cautioned that if investors believed the Treasury was committed to keeping yields low, it could become harder to reverse the intervention later. Druckenmiller noted that yield management often starts as a technical move but can evolve into a policy commitment with lasting implications.
The Treasury has defended the buybacks as necessary for improving liquidity and managing its debt portfolio, with Bessent indicating that the operations might grow beyond the initial $4 billion scale. Meanwhile, financial analysts have pointed out that while the Treasury General Account (TGA) holds around $950 billion in headline figures, only a fraction of this is truly available for spending, according to a report from Yahoo Finance. Citadel Securities labeled Bessent’s approach as financial repression, warning that political considerations could prompt investors to demand even higher yields.
The situation is complicated by the fact that long-term Treasury yields are rising, while short-term rates remain stable, signaling a deeper problem in the financial system. The US government carries roughly $40 trillion in debt, and the artificial-intelligence buildout is creating another enormous demand for capital. Treasury Secretary Bessent has responded with increasingly aggressive tools, announcing that the Treasury Department would at least double long-end buybacks from $2 billion to $4 billion per operation beginning September 9.
Initial market reactions were positive, but that relief was short-lived as geopolitical and fiscal risks mounted. Gold and crypto prices rose as investors sought safer assets amid uncertainty, while Treasury yields remained high. The $4 billion buyback program is a small technical intervention compared to the total outstanding debt of roughly $32 trillion.
Some reports suggested that Treasury officials were considering using funds from the Treasury General Account to finance the expanded buybacks, Seeking Alpha reported. This idea gave the impression of a powerful policy move, but experts noted that the actual usable buffer is much smaller than the headline figure suggests. Even if the Treasury could tap nearly $1 trillion in TGA funds, it would still be constrained by debt ceiling rules and other financial obligations.
The TGA functions more as a daily checking account than a reserve of free cash, with regular inflows and outflows of around $150 billion per day. While the government may not hit another debt ceiling until late next year, this gives Bessent some flexibility to use TGA funds for bond purchases. However, analysts warned that even with such a large potential tool, the Treasury’s actions would not amount to true quantitative easing.
The key difference is that the Fed can create new reserves when buying bonds, while the Treasury must draw from its own accounts. Even if the Treasury used $700 billion to buy back long-term Treasurys, it would only provide a temporary reduction in supply. The market understands that the Treasury will need to replenish TGA balances over time, which limits the long-term impact of such purchases.
Investors may hesitate to sell large amounts of long-term bonds if they are unsure when or how the Treasury will replace them. Some experts believe a simpler and more honest approach would be to reduce the size of new long-term Treasury issuance instead of using buybacks.
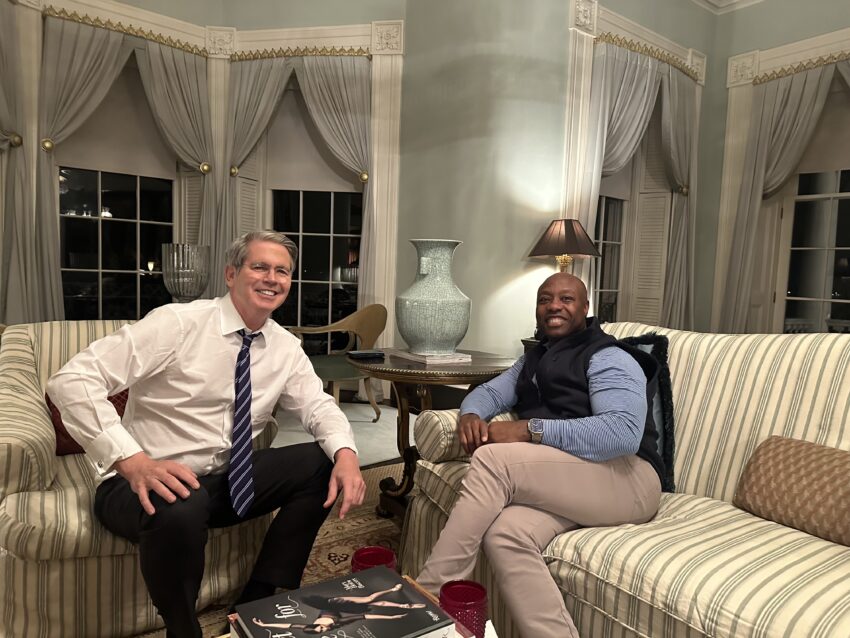
IMAGE: Senator Tim Scott meeting with Scott Bessent, President-elect Donald Trump’s choice for Treasury Secretary.. Photo: Senator Tim Scott / Wikimedia, taken 2024-11-24, Public domain